Human CapitalInvest Today in the Skills You’ll Need Tomorrow
Oliver Sparing
Founder & Head of Trading · TradeNeon
Updated October 2026 · 7 min read
When I started trading, I wanted to know when I would make money from it. Today I ask a different question: What skills am I building, even when the next trade tells me nothing about my progress?
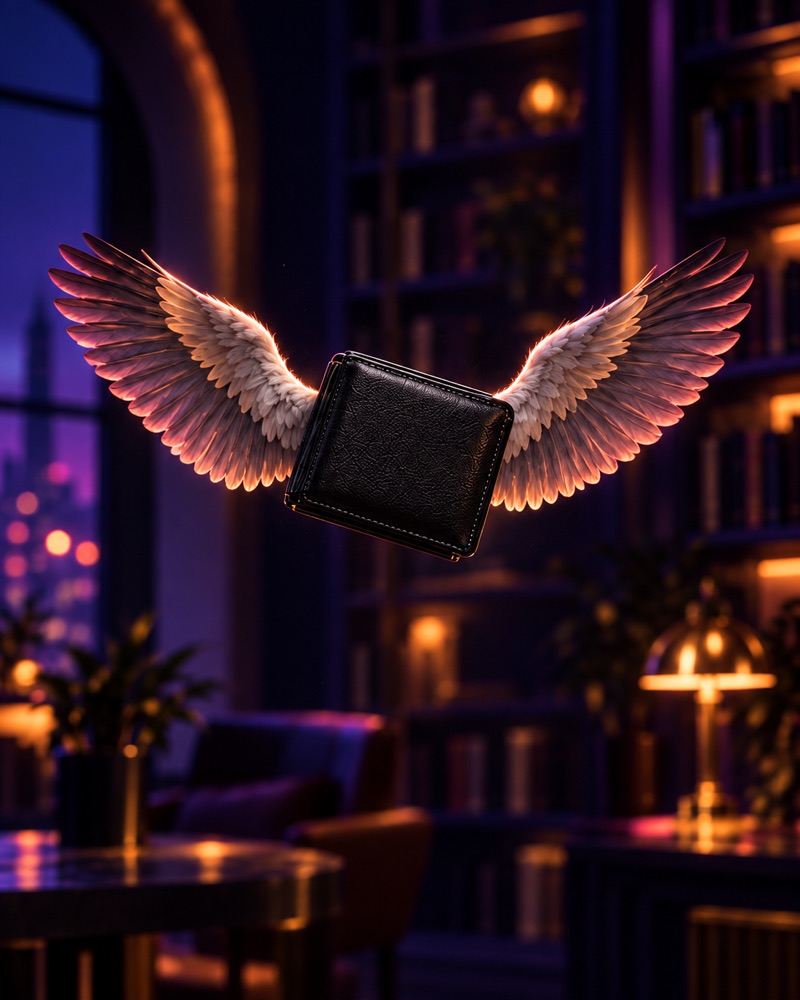
Oliver Sparing and the flying wallets: an AI-created editorial image of his first encounter with the market.Image: TradeNeon
One of my guitar students was called Alex. One day he showed me how EUR 500 had become EUR 4,000 in the market within a few days. His explanation stayed with me: the stock market was like a wallet. You opened it, took out the money and closed it again. I was fascinated. And I wanted to know how he had done it.
The flying wallet echoes Alex’s comparison. A quick gain was a beginning, not a business model. Image: TradeNeon
So I opened a trading account. In one of my first trades, I bet on the DAX, risked too much and added to the position when the market moved against me. Very little of my first deposit was left. Alex could not hold on to his quick gain either. The question we should have asked was: Do we even understand the risk we are taking? Instead, I asked how I could recover my loss as fast as possible.
01
The question of quick profits
People starting to trade often ask, “When will I become profitable?” I understand why. Learning takes time and often money. But one winning trade does not answer that question, and neither does an expensive course. The US investor education site Investor.gov warns that day tradingIn day trading, positions are opened and closed within the same trading day. can lead to substantial losses in a short time. Money needed for living costs or an important reserve does not belong in an experiment with open-ended risk.
02
What investing in yourself really means
After that start, I looked for people I could learn from. At a free brokerA broker carries out market transactions on a client’s behalf. Private investors need a brokerage account to trade. seminar, the first thing I saw was advertising built around quick success and a Porsche. Later I met someone who took time to study company figures and charts. His expectations for possible annual results disappointed me then. I had seen much higher numbers online. I followed the bigger promises and mainly lost time. Looking back, I judged a method by its advertised return before I understood how it worked or whether it suited me.
That is the heart of human capital for me: knowledge, skills and judgement that I develop through learning and practice. The OECD defines human capital as the stock of knowledge, skills and other personal characteristics that help people be productive. A book, a seminar or a training programme can be a starting point. What I learn becomes a skill only when I test it, practise it, recognise mistakes and change my decisions accordingly.
Later I learned to analyse data on commodities, seasonality and futures markets. That suited my interest in precious metals. On a trading floor in London, I saw traders watching many markets at once across several screens. I learned something there about routines and decisions under pressure. I also realised that I did not want to copy that way of trading. That was progress too: I could better distinguish which approach fitted my time, interests and understanding of risk.
My path began in 2011. My swing and options trading became profitable for the first time in 2014; I learned on a trading floor in London in 2017, and reached profitability in day trading in 2018. Today, in 2026, I teach as TradeNeon’s Head Coach. This is my story, not a timetable for anyone else. Profitability is possible, but it takes skill, practice and an understanding of risk. You cannot buy it by enrolling in a course. Read more about my path at TradeNeon.
Today I do not judge progress by one day’s profit alone. Before a trade, I want to be able to say why I am entering, what would invalidate my idea and how much I could lose. Afterwards, I want to distinguish between three things: Was the idea wrong? Did the market behave differently from what I expected? Or did I abandon my own plan? These questions turn an outcome into an experience I can learn from. A gain in the account may be luck. A well-reasoned decision can be examined, even when the individual trade loses.
A trading education programme can provide direction and give you a place to discuss mistakes. It cannot guarantee a shortcut to profitability or a financial payback. Today I would look closely: What exactly is taught? Are losses, costs and limits explained openly? Can the person not only trade but also teach clearly? Germany’s consumer advice centre warns (in German) about trading coaching advertised with rapid, high gains. A good trader is not automatically a good teacher. And a good teacher cannot do the practice or make the decisions for you.
03
What remains of the first EUR 5,000
Years later, at a garden party, my girlfriend’s cousin asked me what he should do with the EUR 5,000 he had saved after finishing his apprenticeship. The question sounded familiar: How can I make as much as possible from it? Today I would divide it into two questions. How much of that money do I need as a reserve? And where do I want to invest for the long term—in assets, in skills, or in both?
For long-term investing, spreading risk matters. It is not just about the number of stocks in a portfolio, but also about the mix of assets and the amount that needs to stay accessible at short notice. A broadly diversified equity ETFAn ETF – Exchange Traded Fund – is an exchange-traded index fund that replicates the performance of the underlying index almost identically. can be one way to save regularly for the long term. It is not a safety guarantee, and a regular investment plan does not “force” anyone to stay disciplined. Germany’s consumer advice centre explains the benefits and risks of ETFs (in German) and puts diversification into context (in German). Precious metals, property, peer-to-peer loansP2P stands for “peer to peer” and in practice refers to the granting of loans between private individuals. and even wine can also be investment ideas; variety alone does not make a choice suitable. You still need to understand each asset’s costs, access and risks.
Investing in knowledge calls for the same care. Books, courses, seminars and workshops can help me explore a subject. I cannot know in advance whether the expense will pay off financially. What I can influence is what I do with it: Do I ask better questions after the course? Can I explain a risk before taking it? Do I follow my rules when the market puts me under pressure? And can I tell when a strategy or a provider does not suit me?
I did not ask these questions from the start. Even after I had found a method, I let someone talk me away from my plan during a silver trade and took a painful loss. I already had technical knowledge. What I lacked in that moment was the ability to stay with a reasoned decision under pressure. That is why a trader’s human capital includes more than market knowledge. It also includes risk awareness, self-observation and a willingness to examine mistakes honestly.
Those skills can matter beyond the next trade. Learning to question promises, limit risk and examine your own way of working can help you make more deliberate decisions outside the market too. That does not translate into a particular account balance. For me, it is still a lasting value: I do not have to control every outcome to take responsibility for how I learn.
Oliver Sparing
Founder & Head of Trading · TradeNeon
Oliver Sparing has been actively trading the financial markets since 2011. His professional roots lie in precious metals trading in Hamburg; in 2017 he learned at a London trading floor. At TradeNeon he leads the day trading and swing trading programmes and is responsible for the trading methodology, with a focus on order flow, market structure and fundamental market data. Level of Interest, Futures Insights and Lab of Trades grew out of this work. Platforms such as ATAS, Bookmap and WH SelfInvest regularly invite him as a guest. All guest appearances
Choosing an ETF depends on your financial planning and investment objective. These six steps take you from selecting a broker to choosing and buying an ETF.
Concept illustrationImage: TradeNeon
6Steps
1 The decision to invest
2 Find a suitable broker
3 Open a brokerage account
4 Savings plan or lump sum
5 Choose a suitable ETF
6 Buy and allow time
The six steps at a glance: From the decision to invest to your first purchase, this guide takes you through each step.
Many people want to build wealth over the long term without continually selecting individual stocksA stock is a security that represents a stake in the share capital of a stock corporation and grants its holder economic and participation rights.. A broadly diversified index ETF can be one component. Its fund management follows the rules of the chosen index; recurring fund costs and broker fees still matter. Reinvested income can generate further income. Performance fluctuates, and losses remain possible.
Long term
Plan equity investments with losses you can afford
Small amounts
Check the provider’s minimum contribution and costs
TER
Compare recurring fund costs
The essentials first
This article describes a long-term investment approach using broadly diversified equity index ETFs. Use money you can do without for an extended period. Your investment horizon depends on your goal and financial circumstances. A long period does not reliably protect against losses; reserves needed in the near term require separate planning.
01
The decision to invest
Before choosing specific ETFs, clarify your income, expenses, reserves and investment objectives. ETF units can normally be traded on an exchange. A short-term sale may, however, realise losses, and execution may become difficult under exceptional market conditions. Plan money for emergencies and foreseeable expenses separately from long-term equity investments.
How much do I earn each month after tax?
How much do I need for monthly expenses and reserves?
How much is genuinely available for long-term investment?
Do I have an accessible reserve suited to my ongoing expenses, potential emergencies and income security?
Which risks can I afford and am I willing to take?
What is an ETF?
An ETF(Exchange Traded Fund) is an exchange-traded investment fund. This article addresses index ETFs that track an index such as the DAX, S&P 500 or MSCI World. Actively managed ETFs also exist. The securities and markets covered depend on the index and fund: a broadly diversified equity ETF may hold many companies, while a country, sector or thematic fund may be more concentrated. Fund assets are held separately from the fund management company’s corporate assets under the applicable legal structure. German Sondervermögen is not liable for the management company’s obligations. This separation does not protect against losses in the investments held.
02
Find a suitable broker
You submit buy and sell orders through your broker or custodian bank. Custody follows the bank or custody arrangement specified in the account agreement. Compare account, order and savings-plan costs, as well as available execution venues. These costs affect your investment’s result.
For the long-term approach described here, we consider broadly diversified equity index ETFs. Compare the costs and execution quality of the venue offered. Exchange trading alone does not make a product low risk: certificates and warrants can also trade on exchanges.
A note on product selection
Service type
Examples
What should you check?
Neo-broker
Trade Republic, Scalable
Plan and account costs, specific savings-plan conditions, available execution venues and support
Online broker or direct bank
ING, Comdirect
Costs for your ETF and order size, account terms, available venues and service
International brokerage
Interactive Brokers
Responsible entity, products and permissions, routing and fee model, market data and tax administration
Important
Check whether your chosen ETF is available in a savings plan and which execution fee applies. Execution without an order fee may still involve product costs and spreadsThe price difference between the bid price and the ask price is called the spread.. Compare the venues actually available and costs in the current price list. Some providers offer multiple execution venues; the choice depends on the specific offer.
03
Open a brokerage account
Account opening and available identification methods depend on the provider and your country of residence. Check the required documents, contractual entity and investment products available to you. After checks and activation, you can deposit money through the specified payment route. The provider explains when deposits become available and any further trading conditions.
Consider trading hours
Compare bid and ask prices before placing an order. Trading time, venue and the markets of the securities held by the ETF can affect the spread. Regular Xetra trading runs from 09:00 to 17:30 German local time; retail investors also have extended trading hours. Check which sessions your broker supports. A particular window does not guarantee the narrowest spread.
04
Savings plan or lump-sum investment?
A savings plan and a lump-sum investment may suit different circumstances. First distinguish newly available regular income from a sum you already hold. Also consider your objective, capacity for losses, costs and whether you can follow the plan during price declines.
Criterion
Savings plan
Lump sum
Starting amount
Provider’s minimum contribution
Consider unit price, fractional-unit rules and costs
Effort
Set up the plan and review contributions and selection as needed
Purchase according to your plan; further purchases as needed
Costs
Execution fees, fund costs and possible spread
Order and venue charges, fund costs and possible spread
Time in the market
Regularly available money is invested incrementally
Existing capital is invested in full earlier
Implementation
Fixed contributions may help you follow the plan
An early price decline after purchase must be financially and personally manageable
Cost averaging
Investing a fixed amount each month buys fewer units when prices are higher and more when prices are lower. This can help you stick to a plan. Splitting an investment does not guarantee a lower purchase price or a higher return. A savings plan funded from future income is also different from deciding whether to invest an existing sum immediately or in stages.
Existing capital: In Vanguard’s historical comparison, an immediate lump-sum investment often outperformed investing the same existing sum in stages. Results depend on the market, period and phasing plan and do not predict your future return. A blanket EUR 5,000 threshold does not determine the choice. Compare costs against your investment amount and choose a process whose loss risk you can bear.
Investment calculator
Explore how your savings contributions could develop over the years.
Index ETFs manage their holdings according to the reference index’s rules. Recurring costs are often lower than those of actively managed funds. Your actual net return also depends on market performance, tracking quality, trading costs and potentially tax. This does not automatically produce a higher future return.
Check the index first
Which countries, sectors and company sizes does it cover or exclude? Then examine the actual fund using its key information document, factsheet and ISIN or German WKN. Similar ETF names may refer to different indices, share classes, income policies or currency hedging. Trading currency alone does not describe the currency risk of underlying holdings.
An example two-ETF portfolio
75 % MSCI World ETF — large- and mid-cap stocks from 23 developed countries
25 % MSCI Emerging Markets ETF — large- and mid-cap stocks from 24 emerging markets
2ETF mix
75 % MSCI World large and mid cap ·23 developed countries
25 % MSCI Emerging Markets large and mid cap ·24 emerging markets
Example allocation: 75 percent MSCI World and 25 percent MSCI Emerging Markets combine developed and emerging markets. The 75/25 allocation is a deliberate illustrative choice. Both components are equity investments whose value can fluctuate substantially.
Indices do not distribute weights equally across countries or companies. Individual markets and large companies may represent substantial proportions. A mix of two equity ETFs therefore does not diversify across multiple asset classes. The fund documents show which securities your chosen ETF actually holds.
One broad fund or two separate components?
An appropriately broad index can also cover developed and emerging markets in one fund, with weights following the chosen index methodology. With two separate ETFs, you set and review the allocation yourself. The suitable option depends on your desired coverage and investment plan.
Feature
What does it mean?
What should you check?
Index
Determines markets, sectors, company sizes and weights
Coverage and risks suited to your objective
TER
Recurring fund costs relative to fund assets
For comparable ETFs, assess alongside tracking quality and trading costs
Fund size
One selection factor; alone it does not prove narrow spreads
Assess assets alongside age, underlying holdings, costs and actual tradability
Replication
Physical holdings or synthetic tracking, such as through swaps
Understand how the method works, its documents and risks
Income policy
Accumulating reinvests income in the fund; distributing pays it out
Choose according to payout needs, reinvestment, costs and your tax circumstances
Assess costs and tracking quality together
The TER is only part of costs. Fund transaction costs, order and venue fees and spreads on purchase or sale may also arise. For index ETFs, tracking difference shows how fund returns differ from the reference index. Recurring costs and other fund effects already contribute to it; TER and tracking difference are therefore not two independently additive fees. A total-cost assessment is also called TCO and is not a single additional charge.
Hypothetical calculation: 0.2 percent of EUR 10,000 is EUR 20 in annual recurring costs assuming constant reference assets. The 0.2 percent is an illustrative parameter, not an actual tariff of a recommended ETF. In practice, recurring costs are reflected in fund assets and performance, and the reference value fluctuates.
Where can you find suitable ETFs?
Two ETF search portals in the German-speaking market are justETF.com and extraETF.com. You can filter ETFs by factors including fund size, replication method and distribution policy. Compare information against the provider’s fund documents. For portfolioThe portfolio is the collective term for all assets owned by a client, a company or an investment fund. tools, check which features are free and which require a different plan.
06
Buy and allow time
Once your investment plan, ETF selection and cost assessment are complete, you can prepare the purchase or savings plan. With EUR 1,000 and an illustrative 75/25 allocation, the target amounts are EUR 750 for MSCI World and EUR 250 for MSCI Emerging Markets. This calculation excludes possible order fees. Whether you can invest those amounts exactly depends on unit prices and your broker’s fractional-unit rules.
Check before placing an order
Specific fund and correct share class: ISIN or German WKN.
Amount or number of units, fractional-unit rules and available account funds.
Execution venue, trading time, displayed spread and expected fees.
Order type and conditions: a limit order sets a price limit and may execute partially or not at all. Savings plans follow the provider’s execution rules.
“We are not talking about two months, but 15 years or more. Following prices every day will drive you to distraction. You are a long-term investor. Take a step back.”
Oliver Sparing — TradeNeon Academy
This personal perspective describes a long-term approach. Whether the period suits you depends on your goal and financial circumstances. A long holding period does not guarantee a positive return. What matters is a sustainable plan that you do not replace in response to every short-term price movement.
Common mistakes when investing in ETFs
Selling in panic, frequently changing ETFs without a plan or making unnecessary transactions can cause costs and additional risks. More ETFs do not automatically mean more diversification: their holdings may overlap. Follow your investment plan and review it regularly and when your financial circumstances change. Minimal activity does not guarantee a permanent optimum return.
Review your plan and allocation
Decide when to review your objective, capacity for losses and portfolio. With multiple ETFs, allocation can drift as prices develop differently. Deliberate review and any necessary adjustment can help keep risk closer to your plan. Consider transaction costs and potential tax consequences. Rebalancing does not guarantee a return advantage and does not require daily responses to price movements.
Frequently asked questions
How much money do I need to start?
Savings plans can start with small amounts; the provider sets the minimum contribution. The appropriate amount depends on your available funds and reserves. For a lump-sum investment, compare unit prices, fractional-unit options, order and venue fees against the amount invested. This does not establish a general EUR 500 minimum investment.
Are my ETF units protected if the fund management company becomes insolvent?
Fund assets and the management company’s corporate assets are held separately under the applicable legal structure. German Sondervermögen is not liable for the asset management company’s obligations. Asset separation depends on legal form and fund domicile, not just physical or synthetic replication. Read the fund documents. This structure does not guarantee the market value of your units or protect against losses in the investments held.
Which ETF should a beginner buy?
One example used in the ETF course combines an MSCI World ETF and an MSCI Emerging Markets ETF. The 75/25 split shown here is an illustration. A suitable allocation depends on objectives and capacity for losses. The two indices cover large- and mid-cap stocks in developed and emerging markets respectively. The securities held by the actual funds selected are listed in their documents.
What is the difference between accumulating and distributing?
Accumulating ETFs reinvest income within the fund. Distributing ETFs pay it out; you can reinvest or use it yourself. Each approach can suit different objectives. Consider your need for payouts, reinvestment costs and personal tax situation. Reinvested income remains part of an investment whose value can fluctuate and decline.
What does an ETF really cost each year?
The TER describes recurring fund costs reflected in fund assets and performance. It is not a complete overview of all costs. Fund transaction costs and broker charges may also arise, including order and venue fees and spreads. A total-cost-of-ownership assessment(TCO) is not a separate additional fee. Compare the key information document, factsheet and price list and, for index ETFs, tracking quality. A TER below 0.3 percent alone does not make an ETF suitable for you.
Which tax rules apply if I am taxable in Germany?
For funds held as private assets in Germany, distributions, advance lump-sum amounts(Vorabpauschalen) and sale gains may be relevant for tax. Accumulating does not automatically mean tax-free until sale. The current savings allowance is EUR 1,000 per person or EUR 2,000 for jointly assessed spouses. For private investors in funds qualifying as equity funds for tax purposes,30 percent of income is generally partially exempt. The conditions depend on the fund and your circumstances. Advance lump-sum amounts already assessed are taken into account when calculating a subsequent sale gain. This context concerns Germany and private fund investments; other countries have different rules.
How long should I remain invested in ETFs?
Your investment horizon should fit your goal, financial circumstances and the risks of the selected ETFs. The long-term equity approach described here requires time and the ability to bear interim losses. Losses remain possible even over long holding periods. Historical index returns depend on the period, currency and inclusion of dividends; they do not guarantee your ETF’s future performance. No universal claim about every 15-year period can be made without a completely defined and verified dataset.
Sources and context
Editorial sources checked 6 October 2026. Historical data and views are identified by their respective periods.
InvStG section 20: Partial exemptionGenerally 30 percent for private investors in qualifying equity funds; official indexed source and consolidated law checked.
EStG section 20: Savings allowanceEUR 1,000 or EUR 2,000 under the stated conditions; official indexed source and consolidated law checked.
ETF AnfängerMSCI WorldETF SparplanPassives InvestierenBroker VergleichZinseszinsCost Average EffektSondervermögen
Oliver Sparing
Founder & Head of Trading · TradeNeon
Oliver Sparing has been actively trading the financial markets since 2011. His professional roots lie in precious metals trading in Hamburg; in 2017 he learned at a London trading floor. At TradeNeon he leads the day trading and swing trading programmes and is responsible for the trading methodology, with a focus on order flow, market structure and fundamental market data. Level of Interest, Futures Insights and Lab of Trades grew out of this work. Platforms such as ATAS, Bookmap and WH SelfInvest regularly invite him as a guest. All guest appearances
Is it immoral to trade commodities on an exchange?
TradeNeon Academy
Originally published · 18 min read
Is trading commodities immoral? This article examines price formation, food supply, speculation and hedging, distinguishing personal arguments from verifiable facts.
Concept illustrationImage: TradeNeon
01
The ethics of futures trading
This article is intended to ease some of your concerns about the topic or give you useful arguments for conversations with friends and family—if you choose to engage in that sometimes exhausting discussion at all.
02
A central criticism of futures trading
One central criticism of speculative futuresA future is a standardized forward contract that obligates the trading partners to a transaction in the future. trading is that the contracts being traded can become detached from the goods actually available. First, however, we need to distinguish between settlement methods: some futures provide for physical delivery, while others are cash-settled. If you do not want delivery, you must observe the exchange and broker deadlines and close or roll your position in time. Automatic liquidation by your broker is not a general guarantee. Profits and losses are settled through clearing. Your counterparty does not have to share either your time horizon or your purpose.
Contracts, delivery obligations and physical backing
The gold market helps illustrate this distinction. The number of derivatives alone does not tell us how much metal must be available for the particular settlement process. Futures, gold ETFs and gold ETCs differ in their legal structures and terms. Some products confer a delivery entitlement; others only provide exposure to price movements. Physical backing does not automatically make you the owner of specific bars. Whether and how a product is backed must be checked for that particular product. A general shortage cannot be inferred from the number of contracts.
The same applies to our money. Commercial banks create deposit money when they lend. There is no general rule allowing them to lend exactly ten times the money they already hold. Regulation, funding requirements and demand for credit constrain lending. Loans can finance economic activity; they do not automatically increase prosperity.
Bank deposits are claims against a bank, not stocks of cash. Large-scale withdrawals can cause liquidity problems; that does not mean deposits are merely imaginary.
Trust is part of the monetary system. Deposit money also has a legal basis and is recorded on balance sheets.
Criticism of futures trading concerns, among other things, possible price distortions and their consequences for people who can barely afford food. But which economic effects can be substantiated, and how should we assess them morally? We need to distinguish these two questions before drawing a conclusion.
03
The Pope and the exchange
Speaking to the FAO on 11 June 2015, Pope Francis criticised the possible effects of financial speculationSpeculation is buying or selling an asset because you expect its price to change. on food prices and poor people. The phrase “This economy kills” comes instead from Evangelii gaudium, published in 2013, paragraph 53. There it refers to an economy of exclusion and unequal incomes. The documents and their contexts must be kept separate. These statements invite an economic and moral discussion; they are not a blanket scientific judgment on every futures transaction.
Our current economic system is, of course, far from perfect, and there are many areas where it needs to improve in the future.
We should also remember the economic and social progress of recent decades. Health, living conditions and incomes have improved over the long term in many countries. These gains are real but unevenly distributed; they do not rule out setbacks.
For a perspective on these developments grounded in data, I recommend “Factfulness” by Hans Rosling, Ola Rosling and Anna Rosling Rönnlund. Published in 2018, the book encourages readers to test widely held assumptions against data. Its historical figures do not, however, replace current datasets.
Extreme poverty has fallen over several decades. According to the World Bank’s September 2026 update, around 824 million people, or 10.1% of the world’s population, lived below the international poverty line of USD 3.00 per person per day in 2024, expressed in 2021 purchasing power parity terms.
Trade and access to markets can support development. Their contribution also depends on institutions, infrastructure, education and the distribution of income. Progress at a global level does not directly reveal how much of it is attributable to the removal of trade barriers.
Factfulness
Global income distribution
International dollars per day ·2011 PPP · logarithmic
EuropeAmericasAfricaAsia/Pacific
Visual reconstruction of the historical estimate. Max Roser / Our World in Data, Data: Ola Rosling / Gapminder · CC BY.Source and context
The original graphic reconstructs income distributions from national income, population and within-country inequality. Income is adjusted for purchasing power and inflation; non-market income is included. Curves were traced visually from that graphic. They represent 1800,1975 and 2015 and are not current measurements.
The same applies to futures markets: their economic function needs to be examined separately.
Global progress
Many health indicators have improved over the long term. According to the current World Bank series, life expectancy at birth rose between 1960 and 2024 from 58.0 to 74.7 years in Vietnam, from 39.6 to 67.6 in Ethiopia and from 46.9 to 65.7 in Ghana. Mortality before the fifth birthday has also fallen globally over several decades, although progress has slowed recently. Developments are not uniform across countries or years. Global life expectancy temporarily declined during the COVID-19 pandemic.
These gains deserve recognition. They do not answer every moral criticism of the economic system or establish the effect of a particular form of commodity trading.
The historical chart below shows estimated global income distributions for 1800, 1975 and 2015. It illustrates how many incomes shifted upwards from very low levels. Income and wealth are different measures, however. The chart establishes neither an even distribution of wealth nor that everyone can meet their needs today. It is a historical approximation in international dollars with a 2011 purchasing power basis, not a distribution statistic for 2026.
04
The influence of speculators
So what influence do speculators have on commodity prices?
Research reaches different conclusions about speculation and commodity prices depending on the market, period and method. A 2014 FAO paper identifies predominantly fundamental causes in several episodes it examines; a 2011 modelling study by Lagi and colleagues instead attributes a substantial role to speculation. It would therefore be too sweeping to deny critics any empirical basis. Such studies need to be read with their respective assumptions and limitations in mind.
International trade can cushion regional crop failures if alternative sources of supply are accessible. At the same time, international price and supply shocks can be transmitted to domestic markets. Transport capacity, trading conditions and inventories are among the factors that matter. Comparing two precious-metal charts therefore does not establish a general effect of free markets on food prices.
Historical comparison: tungsten and gold,1980–2018. Original graphic from the Academy article. Enlarge graphic ↗
Two distinctions are important for the discussion that follows:
A deeper order book can reduce the immediate price impact of a trade; the number of traders alone does not measure this depth.
Liquidity and longer-term price volatility are different characteristics of a market.
More trading can mean more executable orders. Whether a market actually becomes more liquid depends on their size, price and availability. The identity of the participants and how they trade are therefore far from irrelevant.
Market depth and the price impact of orders
Consider a simplified example: you are at a market and want to buy eggs. Three sellers offer eggs of identical quality, each with the same quantity. Seller 1 asks EUR 1 per egg, seller 2 asks EUR 2 and seller 3 asks EUR 3. Let us also assume that no new offers appear and nobody changes their prices. You buy from seller 1 first. Once that seller’s stock is exhausted, you move to seller 2 and then seller 3. This is a constructed teaching example, not a description of an observed market.
Under these assumptions, the lowest available egg price is initially EUR 1. Once those eggs have been sold, it is EUR 2; once that stock is exhausted too, it is EUR 3. At the lowest price, only one seller’s quantity is available at a time. How quickly it sells also depends on how many eggs buyers demand.
Now imagine 30 sellers instead of three, still with the same quantity per seller. The first 15 ask EUR 1 per egg, another ten ask EUR 2 and the remaining five ask EUR 3. All other assumptions stay the same. What changes?
More quantity is now available at EUR 1. With the same demand, it therefore takes longer to exhaust this quantity. This illustrates market depth. It does not prove that every market with more participants experiences less fluctuation over the long term: real exchanges receive new orders, while others are changed or withdrawn.
Exchanges bring buy and sell orders together. A trader who places an executable passive limit order can provide liquidity; an immediately executed marketable order consumes available liquidity. A speculator is therefore not automatically a liquidity provider in every transaction. A liquid futures market can make hedging easier, but it does not guarantee stable commodity prices.
05
The purpose of futures exchanges
Producers, processors and other market participants use futures to hedge price risks. A producer might hedge a selling price, while a processor hedges future input costs. Speculators can take on risks and contribute to trading. How affordable and accessible a hedge is depends on the particular market and its conditions.
Exchange trading can be understood as bringing buy and sell orders together. This auction process helps explain how different interests meet. To assess the price impact, however, order size, market depth and the particular conditions must also be considered. This alone does not provide a general rule for a trader’s influence.
Scalpers, daytraders and algorithmic trading systems often operate over short time horizons. Depending on their orders, they can provide or consume liquidity. Their influence on prices cannot be determined from holding periods alone. Even short-term orders moving in the same direction can have a noticeable price impact in a thin market.
Explore the course
Speculators and price movements
Longer-term price movements depend on several factors, including supply, demand, inventories and expectations. They do not necessarily require a single well-capitalised trader. There is therefore no basis for ruling out the influence of speculators in general. Regulators also consider the risks of excessive speculation; that likewise does not establish that every speculative transaction causes a specific supply crisis.
The historical gold and tungsten charts show different price paths. These commodities differ in their uses and supply structures, among other things. Without matching periods, price definitions and a transparent measure of volatility, no general effect of speculators can be inferred. Tungsten is also not an agricultural commodity. A more volatile chart therefore establishes neither greater power over farmers nor its cause. The illustration should be read as a historical comparison with these limitations.
06
Do prices keep rising?
Another disputed question is whether speculation can affect the price level. It is sometimes claimed that speculators want to drive commodity prices permanently upwards. Yet speculative actors do not have uniform interests. Neither this sweeping attribution nor its complete rejection follows merely from the existence of buyers and sellers.
Investment
Buying a newly issued share can provide capital to the company. If you buy an already traded share on the secondary market, however, the purchase price generally goes to the seller. You acquire an ownership interest in the company and can participate in its development through distributions or price changes, for example. A profit is not certain. A seller can also have very different reasons for selling later: realising a gain, limiting a loss, needing money or changing their portfolioThe portfolio is the collective term for all assets owned by a client, a company or an investment fund.. The sale alone does not reveal their previous returns.
A previous capital gain for the seller is therefore by no means a prerequisite for this trade.
Speculation
Every open future has a long position and a short position. The contract’s price changes affect their profits and losses in opposite directions. Their overall economic objectives can nevertheless differ, for example when a position hedges a transaction in physical goods.
Shares can also be traded on expectations of rising or falling prices. Speculation is not necessarily short-term, and its participants do not all pursue the same direction. The ability to go long or short establishes neither a continuous rise in prices nor its impossibility. Historical charts show particular past patterns; they do not establish a general law under which commodity prices always stay within fixed ranges.
Example: historical maize prices
The chart below uses monthly World Bank reference prices for U.S. maize, yellow, No. 2 grade, f.o.b. U.S. Gulf ports, in USD per tonne from 1974 to 2020. It shows nominal prices in physical commodity trading, not OHLC prices for a particular futures contract or a reconstructed sequence of futures rolls. For the 2007/2008 food-price crisis, the USDA identifies several interconnected factors, including energy and production costs, demand for bioenergy, weather and policy responses. A price chart alone does not determine the contribution of these factors or speculative behaviour, however. The historical series also does not establish that the price level remained unchanged through 2026.
Maize prices 1974–2020
Monthly reference prices · nominal USD per metric tonne
World Bank Pink Sheet: U.S. no. 2 yellow maize, f.o.b. U.S. Gulf ports. This is not a futures OHLC series or an inflation-adjusted chart. World Bank · Daten
The prices shown are not adjusted for inflation. They therefore do not directly reveal how the real purchasing power of a maize price changed. That would require a suitable deflator, a base year and a transparent calculation method. A freely drawn line does not replace this calculation. The chart therefore contains no purported real-price series; it initially allows a comparison of nominal historical reference prices.
Speculators have different interests: some positions benefit from rising contract prices, others from falling prices.
The CoT reports can be used to examine which trader groups hold which open positions in a particular market. Open positions do not directly measure liquidity or the cause of a price movement, however. They do not establish a general dominance of commercial traders in every market.
A futures contract has a long side and a short side.
07
Do higher commodity prices harm poorer countries?
Another criticism concerns the burden higher food prices place on poor households. Yet households are not all in the same position.
Writing for IFPRI in 2014, Derek Headey reported a statistical association between higher domestic food prices and lower poverty after economic adjustments. He also identified uncertainty about the mechanism and possible short-term disadvantages. This is an important finding for the discussion, but it does not establish a universal benefit from every price increase.
A household may produce food, buy food for itself and also earn income from work. Higher selling prices can increase revenue; higher purchase prices add to expenditure. Production costs and possible wage adjustments also matter. Whether a household benefits overall depends on this combination and the period considered. This is precisely why a poor country cannot be assumed to experience the same effect for everyone living there.
A study published in 2023 by Headey and Hirvonen examined 33 middle-income countries over 2000–2019. It found a conditional association between higher domestic food prices and lower poverty, particularly in more agrarian countries. The authors explicitly state that they do not establish causation. The studies also do not demonstrate that futures trading causes this prosperity effect. Futures markets can offer price information and hedging opportunities; actual access and effective use are separate questions. Other research by Headey and Ruel also identifies risks to children’s nutrition from food inflation. Poverty rates and nutritional status are different outcomes that should be considered together.
Digital information services can make market and price data more accessible to producers. But access is not uniform: technology, network coverage, costs and skills create constraints. Information alone does not provide access to a futures market or effective hedging.
Research examines links between speculative behaviour, food prices and supply crises using different methods and reaching different conclusions. A price study does not establish that a single futures transaction causes hunger. Conversely, saying there are no empirical indications at all would be too sweeping. The market, period, people affected and other causes need to be identified.
08
Other causes of supply crises
Infrastructure, storage, distribution, policy interventions, conflict and institutional conditions also need to be considered in supply crises. Their importance depends on the particular case. They deserve attention, but they do not rule out a possible contribution from financial markets in advance. We should therefore not turn a single explanation into an answer to every supply crisis.
Government interventions can disconnect domestic food prices from international markets. Their effects need to be assessed for the particular period: relief within individual countries can amplify international price fluctuations when several countries intervene at once. World-market, spot and futures prices should also not be treated as equivalent without checking. A quantitative country comparison therefore requires comparable products, dates, currencies and an identified price source.
Post-harvest losses are another relevant problem. India’s official 2022 NABCONS survey reports different rates for different products, such as 3.89–5.92% for cereals and 6.02–15.05% for fruit. These figures relate to defined post-harvest losses. They are not a proportion of all food rotting before reaching the market; nor can individual product ranges be combined into a blanket overall rate.
In my view, these issues deserve closer consideration. In a 2015 commentary, Philip Booth argues that the debate should not focus exclusively on financial markets. According to his current profile at St Mary’s University, he is Professor of Catholic Social Thought and Public Policy. His position can contribute a perspective, but it does not replace scrutiny of individual claims. One principle therefore remains important for our own assessment:
Commodity trading cannot be morally justified by a price chart alone, nor can it be blamed indiscriminately for supply crises. What matters is the function a transaction serves and which consequences can actually be substantiated.
Frequently asked questions
How does speculation differ from hedging?
Speculation takes a position in expectation of a price movement. Hedging seeks to limit an existing or planned economic risk, such as a producer’s or processor’s price exposure. The same futures contract can serve different purposes for participants.
Does a price increase prove that speculators caused it?
No. Harvests, production costs, weather, demand, inventories and policy responses can affect prices. A price chart alone does not separate their contributions. A claim about speculative behaviour requires suitable data and an appropriate investigation.
Does speculation always reduce price fluctuations?
No general guarantee can be made. Futures markets can support hedging and price information, but effects depend on market structure and behaviour. A historical comparison of gold and tungsten prices does not establish a general causal effect of speculation on food prices.
Are higher food prices good or bad for poorer people?
Effects can differ between buyers, producers and regions. Higher prices may raise some agricultural incomes while burdening households that buy food. An observed relationship between prices and falling poverty proves neither a general improvement nor that futures trading caused it.
Which data does the historical maize-price chart show?
The maize-price chart shows 564 monthly World Bank reference prices from January 1974 to December 2020 in nominal U.S. dollars per metric tonne. The series concerns U.S. no. 2 yellow maize, f.o.b. U.S. Gulf ports. It is neither a futures OHLC series nor inflation-adjusted. It does not by itself show changes in real purchasing power.
Is trading commodities on an exchange inherently immoral?
The moral assessment of commodity trading depends on the purpose and consequences of the particular transaction. Price hedging, speculation and the supply of physical goods serve different functions. Economic studies can examine consequences; moral conclusions also require an assessment of responsibility and competing interests.
Sources and context
Editorial sources checked 6 October 2026. Historical data and views are identified by their respective periods.
Lagi et al. – The Food Crises (2011)A 2011 modelling study of speculative behaviour and biofuels as potential historical price drivers; not a universal causal finding.
CFTC – Speculative position limitsU.S. market oversight considers price distortion from excessive speculation; this does not establish causation in a specific case or state German law.
CME – Liquidity and order-book depthLiquidity measures include spreads, order-book depth and order price impact, rather than the trader count alone.
IFPRI/Headey – Food prices and poverty (2014)Domestic relative food prices and their association with poverty; the mechanism is uncertain and short-term disadvantages are possible.
St Mary’s University – Philip BoothCurrent university profile: Catholic Social Thought and Public Policy; the previously attributed closing quotation is not verified here.
World Bank – Food Price Shocks (April 2019)Domestic price insulation can amplify global movements; policy has several potential effects rather than being uniformly harmful.
World Bank – Commodity Price Data (Pink Sheet)Official source of World Bank Commodity Price Data. The historical monthly dataset used is linked separately; the chart shows nominal reference prices, not futures OHLC prices or an inflation adjustment.
World Bank – Historical monthly commodity prices, updated 2 October 2026Monthly Prices, column AE/31, Maize, in nominal USD per metric tonne. No. 2 grade, yellow, f.o.b. U.S. Gulf ports. 564 months from January 1974 through December 2020; workbook updated 2 October 2026 and retrieved and checked on 6 October 2026.
TradeNeon is a web-based fundamental analysis software. Find ideal trading opportunities to execute trades with confidence and high success rates! It has never been easier!